
From 15 October 2026, UPI is getting its first real charge in years, but it isn’t landing on the people you’d expect. There is a simple answer to who pays: customers don’t, and neither do small vendors. Large merchants do, and only on bigger bills.
Here’s everything you actually need to know, without the confusion.
What Is UPI MDR From 15 October 2026?
MDR stands for Merchant Discount Rate, a small fee charged on a payment. From 15 October 2026, a limited MDR returns on certain UPI merchant payments, after years of UPI being completely free for everyone.
This isn’t a blanket charge on every transaction. It applies only to specific merchant payments above ₹2,000, and it comes straight out of the merchant’s side, not the customer’s.
In one line: UPI stays free for people. A small fee kicks in only for bigger merchant payments.
Is UPI Free for Customers in 2026?
Yes. Nothing changes for how you use UPI day to day.
- Sending money to friends or family (P2P) stays completely free, no matter the amount
- Paying any merchant up to ₹2,000 stays free, whether it’s tea, groceries, or a mobile recharge
- Small shopkeepers and street vendors collecting up to ₹1 lakh a month through UPI QR pay zero MDR too
The RBI and the Government have both said clearly that banks cannot pass this charge on to customers. About 96% of merchant payments will feel nothing at all, since payments above ₹2,000 make up only a small slice of daily UPI use.
Who Pays UPI MDR Charges From October 2026?
The charge sits entirely with the merchant, and only a specific kind of merchant.
Here’s the simple split:
| S.No | Who | Pays MDR? |
|---|---|---|
| 1 | Customers (any payment) | No |
| 2 | Friends/family transfers (P2P) | No |
| 3 | Small vendors under ₹1 lakh/month via UPI QR | No |
| 4 | Regular merchants, on payments above ₹2,000 | Yes |
NPCI actually created a separate category for small vendors to protect them, called P2PM. If a shopkeeper’s UPI QR collections stay under ₹1 lakh a month, they’re treated as P2PM and pay zero MDR, even on a single large payment of ₹20,000 or ₹30,000. Only after crossing ₹1 lakh a month for three months in a row does an account shift into the regular P2M category, where charges begin to apply.
P2PM vs P2M: What’s the Difference?
This one small distinction decides whether a merchant pays anything at all, so it’s worth understanding properly.
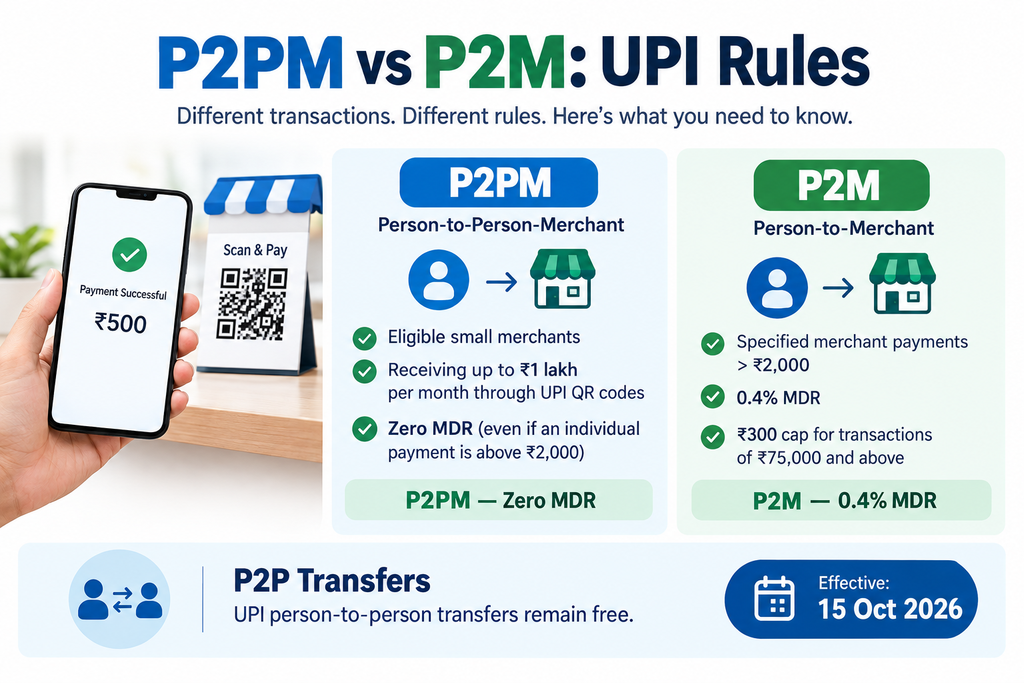
NPCI splits UPI merchants into two categories:
- P2PM (Person-to-Person-Merchant) – built for small vendors. Street sellers, kirana shops, and small suppliers who receive UPI QR payments straight into their own bank account fall here.
- P2M (Person-to-Merchant) – the standard category for larger, formally onboarded merchants.
The difference in simple terms:
| Point | P2PM (small vendor) | P2M (regular merchant) |
|---|---|---|
| Who it’s for | Street vendors, kirana shops, small suppliers | Larger or formally registered businesses |
| Monthly UPI QR limit | Up to ₹1 lakh | No such limit |
| MDR on payments above ₹2,000 | Zero, as long as they stay under the limit | 0.4% applies (capped at ₹300) |
| GST registration needed | No | Depends on the business |
| Need a new QR code | No | No |
The important part: a merchant doesn’t choose this category themselves. The bank or payment app classifies the account based on how much money flows in through UPI QR each month. If a P2PM merchant’s collections go above ₹1 lakh for three months in a row, the account automatically shifts to P2M, and MDR starts applying from there.
One thing worth noting: only UPI QR collections count toward that ₹1 lakh limit. Cash, card, and bank transfers received separately don’t get added in.
UPI Charges for Merchants: How Much and When?
Once a merchant falls into the regular P2M category, here’s what they actually pay:
| Payment Amount | Merchant Pays |
|---|---|
| Up to ₹2,000 | Free |
| ₹3,000 | ₹12 (0.4%) |
| ₹10,000 | ₹40 |
| ₹50,000 | ₹200 |
| ₹75,000 and above | ₹300 (capped, even if 0.4% works out higher) |
A few categories get special treatment. Railways, telecom, insurance, fuel, and similar essential services pay a flat ₹5 regardless of the amount. Mutual funds and stock market payments pay just 0.02%, also capped at ₹300.
For anyone running a business that regularly deals in big-ticket UPI payments, materials, wholesale goods, hospital bills, or bulk orders, this is the part that actually affects your margins. Everyday small transactions stay exactly as free as before.
Why Is the Government Adding This Charge Now?
UPI has grown to a scale nobody expected when it launched. In August 2026 alone, it processed 24.51 billion transactions worth close to ₹30 lakh crore. Running a system that big, securely, isn’t free.
The RBI says this MDR is about long-term sustainability, funding infrastructure, cybersecurity, and future upgrades for a system now used across 11 countries. The Government has been direct about it too: a rollback isn’t on the table, even though the Opposition has pushed back and a case challenging the new rules is currently in the Supreme Court.
Conclusion
The UPI MDR change from 15 October 2026 sounds bigger than it actually is for most people. If you’re a customer, nothing changes, your daily payments stay exactly as free as they’ve always been. If you run a small shop or accept modest UPI payments, you’re protected too, as long as your monthly collections stay under ₹1 lakh.
The only people who’ll actually notice this are larger merchants dealing in big-ticket payments regularly. For everyone else, UPI in 2026 works exactly the way it always has, free, fast, and everywhere.
Frequently Asked Questions
Only specific merchant payments above ₹2,000, once a merchant crosses ₹1 lakh in monthly UPI QR collections. Everyday customer payments and small vendor transactions stay free.
Yes, completely. This charge applies only to merchants, and banks have been instructed not to pass it on to customers in any form.
Larger, formally registered merchants (P2M category) on payments above ₹2,000. Small shopkeepers earning under ₹1 lakh a month through UPI QR are exempt.
No. As long as their monthly UPI QR collections stay under ₹1 lakh, they fall under NPCI’s protected P2PM category and pay zero MDR on every transaction.
Not entirely, if their UPI QR volume crosses ₹1 lakh a month for three straight months, they move into the regular merchant category automatically. Using NEFT or RTGS for very large bills is one way to reduce reliance on UPI for high-value payments